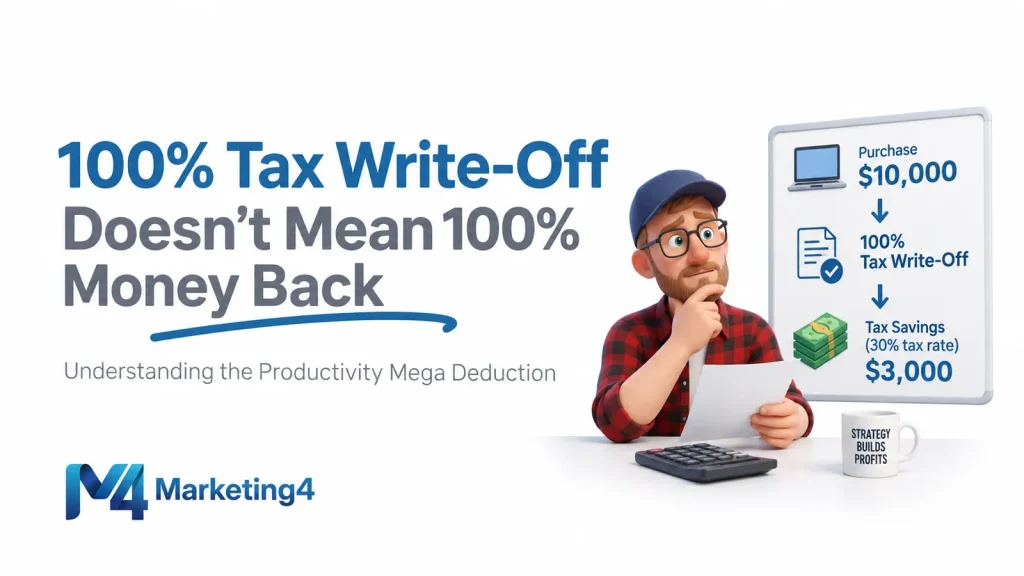
A business owner sees the headline “100% tax write-off” and starts thinking about a $50,000 piece of equipment. It sounds as though the purchase might be almost free after taxes. It isn’t. The owner still has to pay for the machine, and the government’s proposed deduction is calculated against taxable income, not reimbursed against the purchase price.
Canada’s September 15, 2026 Productivity Mega Deduction proposal would let businesses immediately deduct the eligible capital cost of a much wider range of depreciable assets. That could improve cash flow. To understand how much, you need to distinguish the full deduction from the extra benefit created by claiming it sooner than you could under the existing rules.
TL;DR
A 100% write-off means a business may deduct the entire eligible capital cost from taxable income when the asset becomes available for use. It does not mean a 100% refund, grant or tax credit. In a simplified example, $50,000 of qualifying equipment at an assumed 20% income tax rate could produce $10,000 of tax reduction from the full deduction, if the business can use it that year. Some deduction would generally have been available anyway, so the new benefit is primarily earlier tax relief. The measure remains proposed as of September 17, 2026.
Need the overview of the announcement first? Read our guide to Canada’s proposed business investment write-off. If you’re wondering whether a particular machine, computer, vehicle or renovation qualifies, use our purchase-by-purchase eligibility guide. This article is about the dollars.
What does “write-off” actually mean?
For income tax purposes, a deduction reduces income on which tax is calculated. It doesn’t directly reduce tax dollar for dollar. The amount of tax saved depends on the deduction actually claimed and the taxpayer’s applicable tax rate, among other factors.
Imagine a company with $150,000 in taxable income before accounting for its new machine. If it claims an allowable $50,000 deduction and nothing else changes, taxable income falls to $100,000. At a purely illustrative 20% tax rate, the tax calculation falls by $10,000.
| Illustrative company | Without the deduction | With the full deduction |
|---|---|---|
| Taxable income before equipment deduction | $150,000 | $150,000 |
| Equipment deduction claimed | $0 | $50,000 |
| Taxable income after deduction | $150,000 | $100,000 |
| Illustrative income tax at 20% | $30,000 | $20,000 |
| Tax reduction attributable to deduction | — | $10,000 |
This example assumes an eligible $50,000 capital cost, a constant illustrative income tax rate, sufficient taxable income, and no other tax effects. Twenty percent is not a statement about the tax rate of every Canadian small business. The actual federal and provincial calculation can differ.
The business paid $50,000 for the machine and, in this simplified calculation, its tax bill falls by $10,000. Its illustrative after-tax purchase cost is therefore $40,000. That is not necessarily the economic cost of owning it: financing, maintenance, residual value and the productivity it creates also enter the decision.
A deduction, tax credit, grant and refund are four different things
Government announcements sometimes use the word “incentive” for very different kinds of assistance. They shouldn’t be treated as interchangeable.
| Term | What it usually does | Illustration |
|---|---|---|
| Tax deduction | Reduces the income subject to tax. | A $50,000 deduction at a 20% tax rate reduces tax by an illustrative $10,000. |
| Non-refundable tax credit | Reduces tax payable, within applicable limits and rules. | A hypothetical $5,000 credit may reduce tax by $5,000 if sufficient tax is owing. |
| Refundable tax credit | Can sometimes generate a payment even when tax owing is lower than the credit. | Payment and eligibility depend on the specific program. |
| Grant | Provides funding according to a program’s terms. | A grant might pay part of an approved purchase, but none is created merely by this write-off announcement. |
The Productivity Mega Deduction is an immediate-expensing proposal, not a government promise to pay an equipment supplier or repay the business’s purchase price. The Department of Finance backgrounder explicitly describes it as deducting the cost when an eligible asset becomes available for use.
The full $10,000 tax reduction is not necessarily a NEW $10,000 benefit
Suppose the $50,000 machine is depreciable property. Before the proposed change, the business generally would already have been entitled to tax deductions for its cost through capital cost allowance (CCA), often over several years. Existing accelerated-expensing measures can also increase first-year deductions. The new proposal can move those deductions forward.
Here’s a second illustration. Assume that, under the rules applicable to this hypothetical machine before the new proposal, the business could claim $15,000 in the first year and deduct the remaining $35,000 in later years. Those numbers are an illustrative baseline, not the statutory rate for any specified equipment class.
| First-year comparison | Illustrative previous treatment | Proposed immediate expensing |
|---|---|---|
| Eligible equipment cost | $50,000 | $50,000 |
| First-year deduction | $15,000 | $50,000 |
| First-year tax reduction at assumed 20% | $3,000 | $10,000 |
| Additional FIRST-YEAR tax reduction under proposal | — | $7,000 |
| Remaining cost potentially deductible later | $35,000 | $0 |
Under these simplified assumptions, the new measure puts an extra $7,000 of tax relief into the first year compared with the hypothetical previous treatment. But the business would have had deductions left to claim later under the old system. With a constant tax rate and all costs eventually deductible, the total deductions don’t increase from $50,000 to $100,000. Their timing changes.
Earlier tax relief can still have financial value: the business retains cash today rather than waiting for later tax years. The actual incremental benefit depends on the asset’s old first-year allowance, the business’s taxable income and future tax rates. Some types of computers and other assets were already eligible for temporary full first-year deductions; a business purchasing one of those assets may receive little or no additional first-year tax relief from the September announcement.
The correct comparison is therefore proposed deduction versus the deduction already available for that exact purchase, not proposed deduction versus no deduction at all. The CRA’s depreciable-property class guide helps identify the relevant asset class, and an accountant can determine the existing accelerated allowance.
How does an immediate deduction affect cash flow?
Picture a cleaning business replacing aging equipment. It has enough cash to buy the machine, but it also needs money for payroll, insurance and an upcoming seasonal slowdown. If a qualifying deduction reduces its current tax bill sooner, the business may retain more cash during the year of purchase. That can reduce the amount it needs to borrow or leave more room for ordinary operating costs.
Cash flow doesn’t necessarily arrive on the equipment delivery date. The deduction is generally reflected when the relevant tax liability and payments are calculated. Depending on the taxpayer’s year-end, instalments and filing position, the timing of the benefit can differ from the purchase date. The CRA’s available-for-use rules also mean ordering equipment is not automatically the same as having it qualify for a deduction in that tax year.
A quicker deduction is attractive only in context. Spending $50,000 today to reduce tax by an illustrative $10,000 still requires the business to fund the purchase and justify what the equipment will accomplish.
What if the business finances the equipment?
Borrowing doesn’t make a $50,000 machine cost nothing. Assume the same eligible machine is purchased with a $10,000 down payment and a $40,000 equipment loan. The supplier receives $50,000. The business owes the lender $40,000, usually with interest, and must make the required repayments regardless of whether the tax deduction proves available.
| Illustrative financing | Amount |
|---|---|
| Machine price | $50,000 |
| Down payment | $10,000 |
| Amount borrowed | $40,000 |
| Potential first-year capital-cost deduction if eligible | Up to $50,000, subject to applicable rules |
| Loan principal the business still owes | $40,000 |
When the business owns depreciable property, the deduction is generally based on the eligible capital cost and applicable tax rules, not just the amount paid as a down payment. Repaying loan principal is not a second deduction of the same equipment cost. Qualifying interest on money borrowed to earn business income may receive separate tax treatment, subject to the normal rules. Leasing can be different because a lease isn’t necessarily treated as an owned asset; the contract and tax treatment need to be checked.
For an owner deciding whether to finance, a simple monthly cash-flow forecast should include the down payment, loan payments, maintenance, additional revenue or labour savings, and when any expected tax relief can actually be realized. The CRA’s business-expense guidance covers borrowing interest and other expense rules.
What if the company isn’t profitable?
The $10,000 example assumed sufficient taxable income. A company with little taxable income may have little current tax to reduce. A company that already has a taxable loss cannot assume buying equipment creates an immediate $10,000 cash payment from the government.
The draft proposal also distinguishes business structures. For an individual carrying on a business, and for a partnership with individual members, the immediate-expensing deduction is restricted so it generally cannot create or increase a business or property loss from that source. Corporations have different loss rules, and the availability and value of any loss carried into another year depend on their circumstances.
Capital cost allowance is generally discretionary up to the allowable maximum. That means the largest possible immediate deduction isn’t automatically the most useful amount to claim in every tax year. A business with low income, losses or changing tax rates should ask its accountant whether and how much to claim, rather than assume the full amount produces immediate cash savings. The September draft legislative proposals set out the proposed loss restrictions.
What happens if you sell the equipment later?
Depreciation isn’t always the end of the tax story. If the business sells equipment after claiming CCA, the sale may trigger recapture: previously claimed depreciation that must be included in income under the relevant rules. The calculation generally operates at the CCA-class level, so the outcome depends on the class, other assets, proceeds and applicable exceptions.
For a simplified illustration, suppose a business fully deducts the cost of a $50,000 machine and later sells it for $15,000. The sale isn’t automatically $15,000 of tax-free money. Recapture may apply, depending on the class-level calculation and circumstances. The tax treatment of particular passenger vehicles can differ.
This is another reason not to describe a 100% write-off as a permanent reimbursement of the purchase. For details, see the CRA explanation of depreciation recapture and terminal losses.
Should you buy equipment now just to get the deduction?
Consider two hypothetical purchases. One landscaping business has a machine that frequently breaks down, causing cancelled work and expensive rentals. Replacing it may improve reliability and capacity, with the proposed deduction potentially helping its near-term cash position. Another company sees a tax headline and buys the same machine even though its existing equipment is underused and it has no additional work lined up. Both may receive tax deductions if the purchases qualify, but their operating results could be very different.
The investment has to work in the business before the tax treatment is added. Estimate the revenue it could realistically produce, costs it would avoid, staffing and training needs, financing commitments, useful life and resale value. For service businesses, capacity and demand have to match: buying another machine or adding a vehicle creates little value if there isn’t enough profitable work to keep it busy.
This is similar to deciding how much a service business should spend on marketing: start with the business objective and available resources, then choose the spending that supports it. Tax treatment changes the calculation; it doesn’t replace the calculation.
What should you ask your accountant before committing?
Take a real quote, not just an equipment category, and ask for two calculations: the deduction available under current rules and the deduction that would be available under the proposed Productivity Mega Deduction. Ask which CCA class applies, whether the property meets the acquisition and used-property restrictions, when it becomes available for use, whether any passenger-vehicle or business-use limitations affect the claim, and whether the business has enough taxable income to benefit immediately.
Then compare the after-tax cash flows and the financing payments. A $50,000 purchase that makes sense before considering the tax incentive may become easier to fund with earlier deductions. A purchase that doesn’t make operational sense usually doesn’t become worthwhile because part of its cost can be written off.
The announcement is still a proposal
The federal government announced the Productivity Mega Deduction on September 15, 2026, with an intended effective acquisition date of September 15 and immediate expensing in the year qualifying assets become available for use. The Department of Finance has released draft legislative amendments. As of this article’s September 17, 2026 review date, those changes have not yet been enacted. The exact calculation must follow the final law and the taxpayer’s relevant federal and provincial tax treatment.
For the original proposal, see the Department of Finance backgrounder and the draft legislation. This article provides general information and illustrative arithmetic, not a tax determination for a specific business.